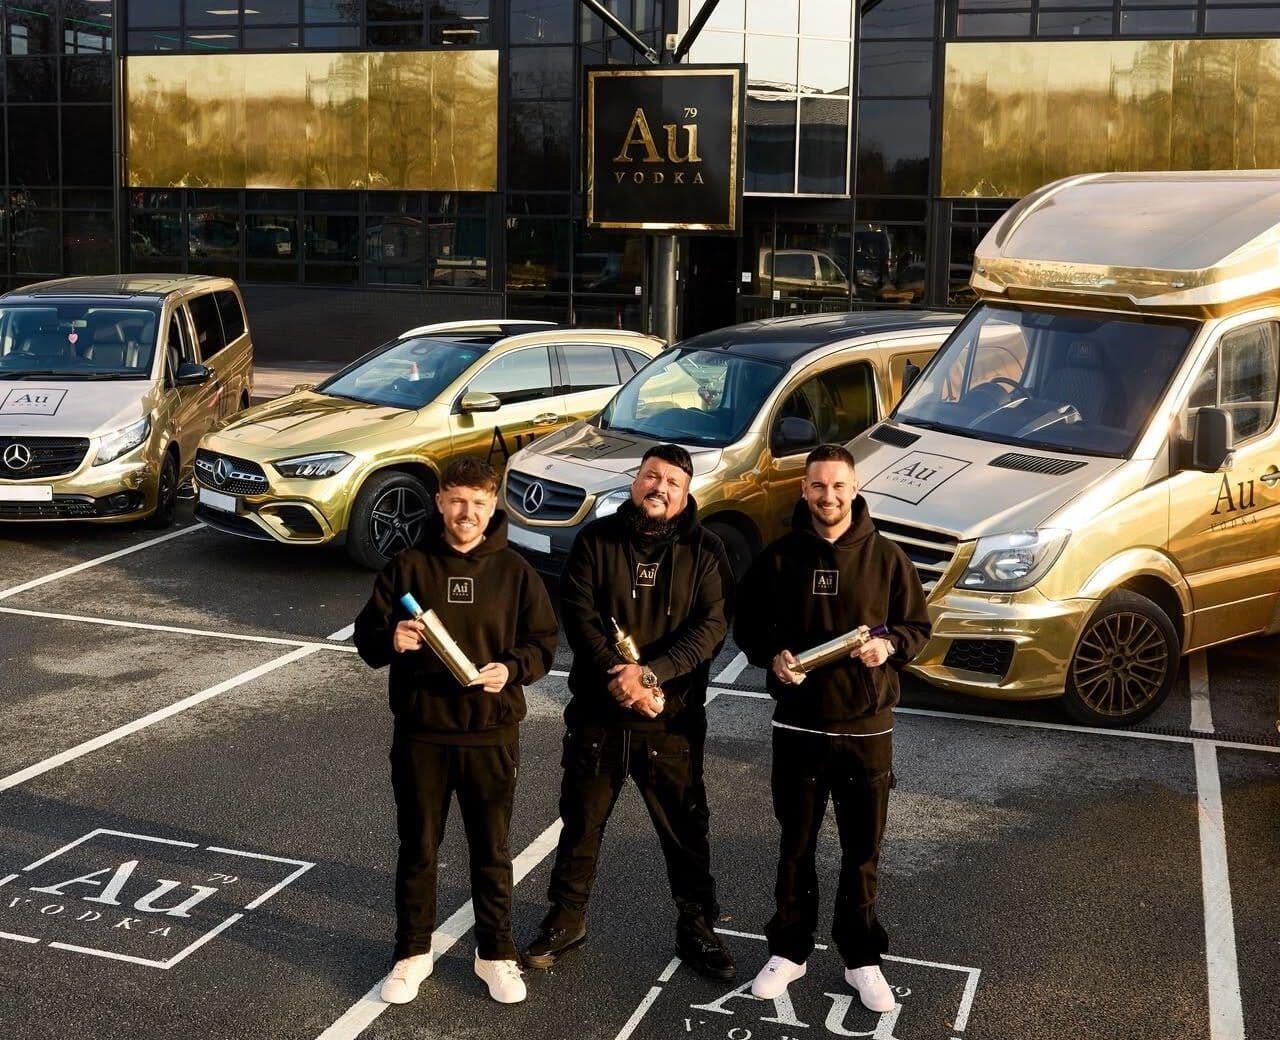
Au Vodka Growth Strategy: What the £500m Sazerac Acquisition Actually Teaches
On 17 August 2026, Sazerac signed a binding agreement to buy Au Vodka. Terms are confidential. Sky News, and every trade title that followed, put the number at around £500m. Ten years earlier, in 2016, the business that number was attached to had sold two thousand bottles. If you're trying to build an au vodka growth strategy playbook from this deal, the gold bottle and the celebrity network are only half the story. The other half is a £3.7m stock-allocation failure that ran through the same set of accounts and got almost no coverage at all.
1. The Scale: What £500m Actually Bought
Before the diagnosis, the numbers. This is the headline shape of the deal and the business underneath it.
| Metric | Figure | Source / Period |
|---|---|---|
| Reported deal value | ~£500m (Sazerac declined to confirm terms) | Sky News, 15–17 August 2026 |
| Estimated founder payout each (Morgan, Quinn) | £100m+ | Multiple trade press, August 2026 |
| Revenue, year to April 2025 | £82.8m, up 27.3% | The Grocer |
| Revenue, year to April 2024 | £65.0m, up 25.9% | The Grocer |
| Revenue CAGR, prior two years | 457% | The Grocer |
| RTD volume growth (year to April 2025) | +206%, to 18.2m units | The Grocer |
| Employees | 80+ (up from 66 average the year before, 50 the year before that) | The Spirits Business, The Grocer |
| UK share of total revenue | 89% | Grocery Gazette |
| Founded | 2015, Swansea | Multiple |
| First bottles sold | ~2,000, in 2016 | Au Vodka company history |
Revenue nearly quadrupled from £43.9m (2021–22) to £82.8m (2024–25) in three years, while the company was simultaneously establishing itself in the US, moving into ready-to-drink cans, and becoming, as of the 52 weeks to 6 September 2025, the UK's second-largest RTD brand by value behind Gordon's. By November 2025, on NIQ data, it had overtaken Gordon's outright to become the UK's bestselling alcoholic RTD brand.
📊 Chart: Au Vodka revenue trajectory, indexed to FY2022
FY2022 (£43.9m)  ██████████████████████████████████████  (100%)
FY2023 (~£51.6m) ████████████████████████████████████████████  (118%)
FY2024 (£65.0m)  ██████████████████████████████████████████████████████████  (148%)
FY2025 (£82.8m)  ███████████████████████████████████████████████████████████████████████████  (189%)
Source: The Grocer, Companies House filings
Every one of those growth numbers is a genuine achievement. None of them is the part of the story worth building your own operating model around. That part is one section down, in a set of numbers almost nobody who covered the au vodka sazerac acquisition mentioned.
This matters to more than one sector. Growsights works across UK mid-market FMCG brands in grocery, beauty and wellness, pet care and fashion, and the mechanism in this article is sector-agnostic: it is what happens to any physical product business the moment demand starts moving faster than the supply chain meant to serve it.
2. Two Thousand Bottles: Why Distribution Wasn't the Story
In 2016, Au Vodka had listings in Selfridges and Harvey Nichols. It had a product people liked. Charlie Morgan and Jackson Quinn had started the business the year before, in Swansea, at nineteen and twenty-one. For the first few years, almost nothing happened.
That's worth sitting with, because it disproves the thing most consumer founders believe. Au Vodka had prestige distribution and it did not create demand. Shelf space in the right shop is not a growth strategy. It's a place for demand to land once you've built it somewhere else.
By March 2017, Au Vodka was arranging terms to sell through the Viking Line ferry fleet, on top of the Harvey Nichols and Selfridges listings. Good doors. Small numbers. The brand didn't move because it was findable. It moved because of four decisions that came after the listings, not because of the listings themselves.
Key insight for retail leaders: If your growth plan starts with "get listed in the right places," you've built a distribution plan, not a demand plan. Au Vodka had the former for two years before it built the latter.
3. Decision One (2015): The Bottle Came Before the Liquid
 Caption: Au Vodka's gold bottle was designed to stand out on shelf and in photographs before the brand had any real distribution. Source: The Whisky Shop
The gold bottle was the first strategic decision Morgan and Quinn made, not a later refinement layered on once the brand had traction. Premium vodka, at the time, was sold almost exclusively in clear glass that looked identical to every competitor on a shelf and worse in a photograph. AU is the chemical symbol for gold. The name and the packaging were the same decision.
The bottle was built to do two jobs simultaneously: stand out physically on a shelf, and be instantly recognisable in a phone camera, at arm's length, in a dark room, at 1am.
That second job is the one competitors underrated for years. It made every customer who photographed the bottle at a party into a distribution channel Au Vodka didn't have to pay for. Jake Paul later got a tattoo of an Au Vodka bottle as a publicity stunt; the gold bottles became a recognised fixture of poolside parties in Ibiza and Dubai. None of that happens with clear glass.
The lesson for mid-market brands: the physical product is a marketing asset before it's a manufacturing decision. If nobody would photograph your packaging, you've built a container, not a brand signal.
4. Decision Two (2017): They Sold Equity for Access, Not Money
Two years after founding the business, Morgan and Quinn approached DJ Charlie Sloth, then a Radio 1Xtra presenter, on Instagram, asking for nothing more than for him to try a bottle. He liked it enough to buy into the business as an investor.
What Au Vodka bought with that equity was not capital. It was a contact book. Sloth put the product directly into the hands of musicians, celebrities and creators who reached exactly the audience the gold bottle was designed to be photographed by.
"In return, Sloth got Au's products into the hands of musicians, celebrities and influencers who helped grow the brand's appeal on social media." — The Grocer, November 2025
Most founders raise money and then go looking for reach, treating capital and distribution as sequential problems. Au Vodka reversed the trade: it paid for access with equity, and let the access generate the growth capital would normally have been used to buy through paid marketing. It is, of the four decisions, the least copied, because it requires giving up ownership before the business has proven it deserves the multiple that ownership will eventually be worth.
5. Decision Three (2019): The Fredo Collaboration
The first flavoured expression, black grape, was built with the rapper Fredo rather than designed for a demographic. That distinction matters more than it sounds. A demographic is a market segment you're guessing about. A named collaborator is a specific audience who gets to treat the launch as theirs.
In December 2019, Au Vodka sold 10,000 bottles of the black grape flavour, more than it had sold across the previous eleven months combined. This is the point the growth curve turns from gradual to exponential.
📊 Chart: Monthly bottle sales, indicative shape before and after the black grape launch
Jan–Nov 2019 (11 months combined)  ████████████████  (<10,000 units)
Dec 2019 (single month)            ████████████████████████████  (10,000 units)
Source: figures as reported by The Drinks Business, based on Au Vodka company disclosure
This is the note that's easy to misread as an influencer-marketing story and harder to correctly read as a distribution decision: a named collaboration doesn't just add reach, it collapses the time between "product exists" and "specific audience feels ownership of it." That collapse is what shows up on a stock ledger a few weeks later as a demand spike nobody forecast.
6. Decision Four (2021): Cans, and the DTC to Wholesale Transition
In 2021, Au Vodka launched ready-to-drink cans and moved from a standing start to a top-five UK RTD brand. It is now, on its own account, the most-followed spirits brand on TikTok. By 2026 it was running co-branded RTDs with Tango into Tesco and the wholesalers, ahead of a wider rollout that includes Asda and Morrisons.
There's a specific crossover worth marking on your own timeline, because it changes what kind of visibility problem you have: the point where you stop being DTC-led and become wholesale-led. This dtc to wholesale transition is the single most consequential structural shift in the whole story, and it's the one least discussed in the coverage of the deal.
While a brand sells primarily through its own site, it can see everything: every order, every postcode, in real time. The moment volume shifts to wholesale and grocery, that visibility ends. The product is in Tesco, Morrisons, Costco and Booker, and what comes back is a weekly file describing something that already happened. Au Vodka crossed that line around 2021, at the same moment cans took the brand into a completely different volume band. Cans didn't just add a channel. They removed the founders' real-time view of their own demand at exactly the point demand became hardest to forecast.
7. The Geography Lesson: Three States, Not Fifty
The international sequencing deserves its own section, because most UK brands get international expansion wrong in a specific, avoidable way: they treat "enter the US" as one decision rather than fifty.
When Au Vodka entered the US in August 2022, it did not launch nationally. It launched in three states, Georgia, Florida and Texas, through distributor RNDC, with shelf presence in around 80 Total Wine & More stores. The company's own launch announcement reported over $1m of revenue in the first ten days in Georgia and thousands of cases depleted inside a month. Those are Au Vodka's own figures, released in its own press materials, so they should be read as a company claim rather than an independently verified one, but the shape of the decision underneath the number is the actual lesson, independent of how large the number was. This narrow-first approach is the template for any au vodka us expansion case study worth studying.
| Expansion phase | Market | Approach |
|---|---|---|
| Phase 1 | UK | Full national distribution, built over years, following the four core decisions |
| Phase 2 | US, Georgia, Florida, Texas only | Single distributor (RNDC), ~80 Total Wine & More doors, demand mechanic tested narrowly |
| Phase 3 | ~40 international markets | Rolled out only after the US mechanic was proven, biggest export markets Germany, Netherlands, Spain |
From three states, Au Vodka reached roughly 40 international markets. UK first, three US states second, everything else third. Not a global launch, a sequence, with each phase used as evidence for whether the next phase was worth funding.
Ask yourself: if you had to prove your growth mechanic in three postcodes before you were allowed to touch a fourth, could you? Or would you find out, the way most brands do, only after national stock commitments were already placed?
8. The Read Most People Take, and Why It's Incomplete
The obvious reading of this story is an influencer story: gold bottle, celebrity network, TikTok, exit. That reading isn't wrong. The brand-building was genuinely excellent, and the social strategy was ahead of the category by years, most operators in consumer goods would take that outcome without hesitation.
It's incomplete because of a number that ran in the same set of accounts and received almost no coverage next to the acquisition headlines.
In the year to 29 April 2024, the year revenue climbed to £65.0m and the brand was closing in on category leadership, operating profit fell 95.1%, to £5.1m, driven substantially by exceptional costs. The Grocer reported £3.9m of exceptional costs for the period, of which £3.7m was attributed directly to what the company itself described as "excess inventory provisioning in relation to excess stock levels… compared to past, current and forecasted rates of sale." Administrative expenses jumped 83.2% to £13.5m over the same period. Post-tax profit fell from around £8.4m the year before to £3.9m. This is the clearest documented case of fmcg overstocking tied directly to a demand-led growth spike that we've seen in a set of public UK accounts this year.
| Financial line | Year to April 2023 (approx.) | Year to April 2024 | Change |
|---|---|---|---|
| Revenue | ~£51.6m | £65.0m | +25.9% |
| Post-tax profit | ~£8.4m | £3.9m | Roughly halved |
| Operating profit | Higher base | £5.1m | -95.1% |
| Administrative expenses | Lower base | £13.5m | +83.2% |
| Exceptional costs | Minimal | £3.9m (£3.7m excess-inventory provisioning) | New line item |
📊 Chart: The same year, two stories
Revenue growth         ████████████████████████████████████  +25.9%
Operating profit fall   ████████████████████████████████████████████████████████████████████  -95.1%
Source: The Grocer / Companies House, year to 29 April 2024
By the following year (to April 2025), operating conditions had normalised somewhat, pre-tax profit rose 31.3% to £6.7m as the exceptional costs weren't repeated, but the pattern in the FY24 accounts is the one worth studying, because it's the one that will recur for any brand riding a similarly steep curve.
This is not a story about a brand getting the strategy wrong. Given the choice between a gap on shelf in the year you're winning new listings and too much stock sitting in the warehouse, most commercial directors will choose the stock, every time. The exit valuation nine years later suggests they were right to. But the overstocking cost is not an unrelated misstep sitting alongside the growth story. It is the direct, predictable consequence of the exact strategy everyone now wants to copy, and almost nobody says so out loud.
9. Why Demand-Led Growth Breaks Supply Chains: The Mechanism
Here's the mechanism, stated plainly, because it's the part that transfers to every other category.
Demand-led growth arrives before your supply chain has a shape to match it. When demand is created by a video going round rather than a promotional calendar planned six weeks out, it is spiky, regional, channel-specific and short-lived. It appears in some postcodes and not others. It shows up in convenience before it shows up in grocery, online before offline. It can be finished in a fortnight. A production decision, by contrast, is national, slow to reverse, and expressed as a single aggregate number on a forecast spreadsheet.
So a business responds to a spike it cannot precisely locate by making more of everything, everywhere. Stock lands where it was already covered because that's where the existing replenishment routes point. It doesn't reach where it was empty, because nobody built a route there yet. The result is a business that is genuinely overstocked in aggregate and genuinely out of stock in the specific stores that mattered, at the same time, for the same underlying reason.
 Caption: National stock cover numbers can hide store-level failures in both directions at once. Source: The Moodie Davitt Report
Key insight for retail leaders: Overstock and stockout are not opposites, and they are not a trade-off you can dial between. They are the same failure, measured at two different altitudes. Finance sees the working capital sitting in a warehouse. The account team sees an availability score falling in the stores that were supposed to be selling out. Nobody in the business sees that both numbers describe the exact same pallet, sitting in the wrong place.
This is the diagnosis a P&L alone will never surface. A finance team reading "£3.7m excess inventory provisioning" sees a forecasting failure to correct next quarter. What it's actually showing is a structural blind spot: national-level stock planning trying to serve store-level, video-driven demand, with no layer translating between the two. Growsights exists specifically to build that translation layer, weeks, not quarters, and store-level rather than national.
10. What to Copy, and What Not To
Not every decision in this story generalises equally well. Here's the split.
Copy:
- A physical asset designed for a camera, not just a shelf, packaging that does marketing work, not just containment
- Equity traded for access rather than capital, when the access is a genuine, specific audience rather than a vague promise of "exposure"
- Product built with a named audience, not designed for a demographic
- Market entry sequenced narrowly enough that the demand mechanic is proven in a handful of stores or states before distribution is scaled nationally
Don't copy uncritically:
- Treating a national production number as the right response to a regional, video-driven demand spike
- Assuming that because the growth strategy worked, the supply chain built to support it was also working, the accounts say otherwise
- Waiting for a full financial year to discover the stock was in the wrong place, rather than tracking allocation weekly while a launch is live
11. The Number to Build: Dispersion of Cover, Not Weeks of Cover
If you're a brand approaching the DTC-to-wholesale crossover described in Section 6, the metric that matters is not "weeks of stock cover" as a single national figure. It's the dispersion of that cover across individual stores, an inventory allocation fmcg problem, not a production one.
Take your best-selling SKU. Calculate days of cover by store. Compare the top decile of stores against the bottom decile. National cover of six weeks means nothing if your worst-performing decile is sitting at three days of cover while your best-performing decile is sitting at fourteen weeks. That's not a production problem. It's an allocation problem, and producing more stock makes both ends of that distribution worse, not better, more stock piles up where it's already overstocked, while the stores running on three days still don't get replenished in time.
| Store decile | Days of cover (illustrative) | Diagnosis |
|---|---|---|
| Top decile | 14 weeks | Overstocked, capital tied up, markdown risk |
| Median | 6 weeks | Looks healthy in national aggregate |
| Bottom decile | 3 days | Stockout risk, the demand that mattered isn't being served |
| Spread (top ÷ bottom) | ~32x | Allocation failure, not a production shortfall |
Growsights' working threshold: if the spread between top and bottom decile exceeds four times, stop the next production increase and fix allocation first. Put that number in front of whoever signs off the production plan directly, not the account team, not finance, who each only see half the picture. Track it weekly while demand is spiking. Monthly the rest of the time.
This is the exact blind spot RetailFlow AI is built to close: connecting Tesco, Sainsbury's, Asda, Ocado and Waitrose portal data with warehouse and distributor feeds into one store-level view, so a national cover number never gets to hide a three-day stockout sitting inside a fourteen-week overstock. For a fuller picture of how this shows up across UK retail more broadly, see our piece on phantom inventory in UK retail.
12. What We're Watching Next
The open question, now the deal is signed, is what Sazerac believes the actual problem was. It owns more than 500 brands and distils internationally, Buffalo Trace, Eagle Rare, Fireball, Southern Comfort, SVEDKA, and BuzzBallz, which sat directly ahead of Au Vodka in the UK RTD rankings before this deal. Sazerac has just bought a business whose growth outran its ability to place stock correctly. Whether it invests in more capacity or in better allocation are two different investments entirely, and the choice will say something about what the acquirer diagnosed.
We should also say plainly what we don't know. Nobody outside Au Vodka has visibility into how its stock was actually distributed store by store, and nor do we. What's public is the pattern: soaring sales, halved operating profit, exceptional stock costs, all landing in the same financial year. That pattern is common enough in fast-scaling consumer brands that it's worth checking against your own numbers, whatever sector you're in.
Key Lessons for Retail Leaders
Lesson 1: Distribution Doesn't Create Demand, It Waits for It
Au Vodka had Selfridges and Harvey Nichols listings for two years before anything moved. The listings weren't the growth engine; they were infrastructure sitting idle until the brand-building and the celebrity access created something for that infrastructure to carry.
Ask yourself: are you chasing better shelf placement because you've already proven demand, or because you're hoping placement will create demand you haven't proven yet?
Lesson 2: The DTC to Wholesale Transition Is a Visibility Event, Not Just a Volume Event
The moment a brand's volume shifts meaningfully into wholesale and grocery, real-time order data disappears and is replaced by weekly retailer files describing the past. Most founders notice the revenue change at this crossover. Few notice the visibility change, until a year-end account shows an exceptional cost line.
Ask yourself: at what point in your growth did you stop being able to see your own shelf, and what did you replace that visibility with?
Lesson 3: National Aggregates Hide Store-Level Failures in Both Directions
A healthy-looking national weeks-of-cover figure can simultaneously describe stores that are dangerously overstocked and stores that are stocked out, because the average erases both. The fix isn't a better national number. It's dispersion, tracked by decile, by SKU, by store.
Ask yourself: if you pulled days-of-cover by store for your best SKU today, do you know what the spread between your best and worst decile would look like, or would that be the first time anyone in the business had asked?
Actionable Recommendations
For Retail Business Owners and CEOs
- Before your next big marketing or influencer push, model what a regional demand spike does to your national stock plan, not in theory, in your actual SKU-by-store data
- Track dispersion of days-of-cover by store for your top 3–5 SKUs, not just a national average, especially once you cross into wholesale or Big Four grocery listings
- Set an internal allocation threshold (Growsights uses 4x top-to-bottom decile spread) that triggers a stop on production increases until allocation is fixed
- If you're approaching the DTC-to-wholesale crossover, build a replacement for the real-time order visibility you're about to lose before you lose it, not after
For B2B Leaders and Suppliers to Retail
- When a client brand is scaling fast on social-led demand, flag the allocation risk early, a supplier who raises this before the accounts show it becomes a genuinely trusted partner, not just a vendor
- Build weekly (not monthly) stock-dispersion reporting into any fast-growth account, because monthly cadence is too slow to catch a spike that resolves in a fortnight
- Separate the production conversation from the allocation conversation in every planning meeting, they get treated as the same decision far too often, and that's exactly where this failure mode lives
Final Summary
| Failure Category | What Went Wrong | What Your Business Should Do |
|---|---|---|
| Demand forecasting | Video-driven, regional demand spikes were met with a single national production response | Model regional/postcode-level demand separately from national aggregate forecasts |
| Stock allocation | Stock landed where existing routes already covered, not where new demand appeared | Track days-of-cover dispersion by store decile, not just national weeks-of-cover |
| Visibility loss | Real-time DTC order data disappeared at the wholesale crossover, replaced by weekly retailer files | Build a store-level visibility layer before volume shifts meaningfully to wholesale |
| Governance | Production and allocation were treated as the same decision, reviewed by finance and account teams separately | Put dispersion numbers in front of whoever signs the production plan directly, weekly during spikes |
| Financial signal | Overstocking was found in the year-end accounts, a year after the fact, as a £3.7m exceptional cost | Monitor the P&L equivalent of dispersion monthly, so it's caught in-quarter, not in the annual filing |
Grow Your Business With Integrated Data and Operational Intelligence
Au Vodka's £500m exit is a genuinely earned outcome built on four copyable decisions. The overstocking line in the same accounts is the cost of scaling those decisions without a store-level view of where stock actually needed to be. Growsights exists to close exactly that gap for UK mid-market FMCG and D2C brands selling through Tesco, Sainsbury's, Asda, Ocado and Waitrose: turning fragmented retailer, warehouse and distributor data into decisions about what to do on Thursday, not reports about what happened last month. If you're approaching your own DTC-to-wholesale crossover, or you've noticed your national stock numbers look healthier than your regional availability feels, start a conversation with us. For more on the metrics that actually drive these decisions, see the retail inventory KPIs that actually drive decisions, and for more on how we work, see how we work.
FAQ
What is Au Vodka's growth strategy?
Au Vodka's growth strategy rested on four sequenced decisions: a gold bottle designed as a photographable marketing asset, equity traded for celebrity access rather than raised as capital, product launches built around named collaborators rather than demographics, and international expansion tested narrowly (three US states) before being scaled globally. The au vodka growth strategy that gets copied is the demand-generation playbook; the part that gets missed is that the same growth outran the supply chain built to support it.
What is the Au Vodka Sazerac acquisition worth?
Sazerac signed a binding agreement to acquire Au Vodka on 17 August 2026 in a deal reported at around £500m, though neither company has confirmed the exact terms. The au vodka sazerac acquisition brings the Welsh RTD brand into a portfolio that already includes BuzzBallz, Buffalo Trace and Southern Comfort.
What caused Au Vodka's overstocking problem?
In the year to April 2024, Au Vodka recorded £3.9m in exceptional costs, of which £3.7m was attributed to excess inventory provisioning against stock levels that outran actual and forecast sales rates. This is a textbook case of fmcg overstocking: national-level production responding to a regional, social-media-driven demand spike, rather than store-level allocation matching stock to where the demand actually was.
What happened when Au Vodka made the DTC to wholesale transition?
As Au Vodka's ready-to-drink cans pushed the brand into Tesco, Asda and Morrisons from 2021 onward, the founders lost the real-time order visibility they'd had as a DTC-led business. The dtc to wholesale transition replaced live order data with weekly retailer files describing demand that had already happened, exactly when demand became hardest to forecast.
How did Au Vodka approach its US expansion?
Au Vodka's US expansion launched in August 2022 in just three states, Georgia, Florida and Texas, through a single distributor and around 80 Total Wine & More stores, before rolling out to roughly 40 international markets. The au vodka us expansion is a model for sequencing: prove the demand mechanic narrowly before committing national or global stock.
Research sources: The Grocer (multiple: acquisition news, FY24 results, FY25 results, founder interview); The Spirits Business; The Drinks Business; BeverageDaily; BevNET; Grocery Gazette; Companies House filings (via press reporting); Au Vodka company launch announcement (BevNET/PR Newswire, 2022, figures attributed as company-sourced).
Published by Growsights | Retail Intelligence and Growth Engineering | Point of View